Time to Pay advice
Why Has HMRC Rejected My Time to Pay Proposal?
Understand why a proposal may be refused and what a revised submission needs to address.
Read article →Struggling to pay VAT, PAYE or Corporation Tax? A Time to Pay arrangement may let a viable business repay tax arrears in manageable instalments. We’ll help you assess what is realistic and understand your next steps.
Free initial advice · No obligation · Nationwide support
A Time to Pay arrangement is an informal agreement with HMRC to pay specified tax debts over an agreed period, usually through monthly instalments.
It can help a business through temporary financial pressure where the underlying trade remains viable. HMRC needs to be satisfied that the proposal is affordable and that the company can clear the debt.
We review the business’s position, explain whether a proposal is realistic and, where appropriate, support negotiations with HMRC.
Explore your options for HMRC debt →Seek advice early if tax payments are slipping or HMRC has started contacting you about arrears.
Book a free consultationAnswer a few questions for an initial indication of whether a Time to Pay arrangement may be suitable for your business.
The checker is a guide to your next steps. It does not submit a proposal to HMRC or confirm approval. Our team can review your circumstances and explain the available options.
Prefer to discuss it? Arrange a free consultation or call 0161 546 8143.
For limited companies, common Time to Pay discussions involve the following HMRC debts.
Overdue VAT liabilities can create significant pressure on cash flow. Any proposal needs to allow for future VAT as well as the existing balance.
Payroll-related arrears should be reviewed alongside current wages, employer costs and upcoming payroll tax payments.
A repayment proposal may cover outstanding Corporation Tax where the company cannot pay in full and the plan is supported by its financial position.
Self Assessment and other tax liabilities may also have payment-plan options. This page focuses on company tax debts.
A repayment plan needs to solve the problem without leaving the business unable to meet its next bills. The important question is what your cash flow can sustain.
If losses are continuing or debts to several creditors are increasing, a wider review may be needed.
Gather the information that shows both the current position and the basis of your forecasts.
We help you explain the figures and identify assumptions that need supporting evidence.
Clear information and realistic repayments give HMRC a proposal it can assess. We guide you through the practical steps.
We review all HMRC balances, overdue returns, creditor pressure and the reasons the tax debt arose.
We examine cash flow and the business’s prospects, including ongoing bills and future tax payments.
Build a clear proposal using realistic forecasts, current accounts, bank statements and details of assets and funding.
Where appropriate, we support discussions with HMRC and respond to questions about the repayment offer.
If HMRC agrees, check the liabilities covered, instalments, payment dates, interest and any conditions.
Maintain payments and returns, monitor cash flow and contact HMRC promptly if circumstances change.
An agreement must work for the whole business throughout the repayment period.
HMRC expects business tax debts to be cleared as quickly as realistically possible. Periods over 12 months are exceptional and need a strong, evidenced case.
Applicable late-payment interest continues even when HMRC agrees Time to Pay. Allow for it when assessing the total cost and affordability.
The business must meet the arrangement’s conditions, file future returns on time and pay new liabilities as they fall due. Contact HMRC if circumstances change.
No repayment period or monthly instalment is guaranteed. HMRC assesses the proposal and may ask for further information.
Read HMRC’s payment-plan guidance →A repayment offer can be refused because the instalments are too low, the period is too long or the evidence does not show that future tax bills can be paid.
Molly explains what to review before making a revised proposal and when to consider other options.
Read the article and watch the video →If repayment is not sustainable, we explain the alternatives. These may include funding or operational changes, alongside formal procedures where appropriate.
A CVA may be considered where a viable company needs a formal proposal to address wider creditor debts. Suitability and creditor support need careful assessment.
Explore CVAs →Administration may be relevant where a rescue or business sale is possible and a formal insolvency process is needed.
Explore administration →If the company cannot recover, a CVL may provide a structured way to close an insolvent business and deal with its affairs.
Explore CVLs →Contact Molly promptly with the notice, any hearing date and HMRC correspondence. An online checker or a pending proposal does not resolve urgent deadlines.
Get advice from Molly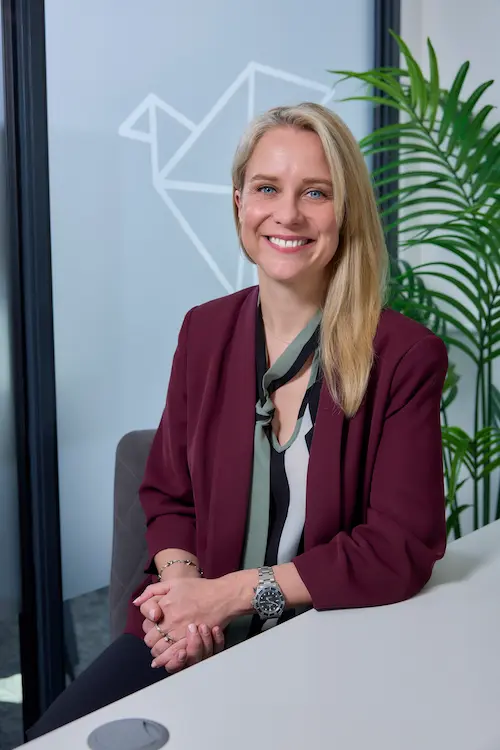
Molly Monks F.I.P.A. is the founder of Parker Walsh and a Licensed Insolvency Practitioner with more than twenty years’ experience in insolvency and corporate restructuring.
She works with directors to understand what caused the arrears, what the business can afford and whether a Time to Pay proposal offers a realistic way forward.
Our in-house team supports directors nationwide from Bramhall, with consultations by phone, video or in person.
Explore proposal preparation, rejected requests, real case experience and the alternatives to an HMRC repayment plan.
Understand why a proposal may be refused and what a revised submission needs to address.
Read article →Explore repayment, restructuring and business-sale options when tax debts become unaffordable.
Read article →Compare an informal HMRC agreement with a formal company restructuring proposal.
Read article →Read how detailed forecasts and negotiation helped one viable business reach a sustainable agreement. Outcomes depend on each case.
Read case study →Understand how HMRC debt recovery can escalate and why early advice matters.
Read article →Learn what happens when tax arrears are left unresolved and what directors should do next.
Read article →Read the official guidance on arranging instalments, the information needed and what happens if you cannot agree a plan.
Read the GOV.UK guide →For directors facing a petition: understand the urgent steps, Court process and practical risks.
View the free guide →If recovery is not possible, understand the CVL process, your responsibilities and the alternatives to discuss.
View the free guide →If you are unsure what your business can afford, use the checker or arrange a confidential conversation with Molly.
No. HMRC considers the company’s position and the proposed repayments individually. Our checker gives an initial indication; only HMRC can agree an arrangement.
The period depends on affordability and the evidence. For business taxes, HMRC normally expects less than 12 months; longer periods are exceptional. There is no entitlement to the term you request.
No. It spreads payment of the agreed liabilities. The tax remains payable in full, and applicable late-payment interest continues.
Yes. You can approach HMRC yourself, and some debts may be eligible for an online payment plan. Professional support may help when the figures are complex, an earlier proposal has failed or wider financial problems need to be reviewed.
Ask for the reason and consider whether a revised proposal can address it with reliable evidence. If the repayments remain unaffordable, seek advice on alternatives rather than repeatedly offering amounts the business cannot maintain.
Contact HMRC promptly and explain what has changed. It may review the arrangement, but default or failure to meet its conditions can lead to cancellation and debt recovery.
Do not assume that a request or voluntary instalments create an agreed plan. Confirm the position with HMRC. A Time to Pay arrangement also does not resolve debts owed to other creditors.
The checker and initial consultation are free. If you ask us to prepare a proposal or support negotiations, we explain the scope and professional fees before you agree to proceed. Fees are separate from the tax and interest owed to HMRC.
You can, but the checker does not deal with urgent Court deadlines. Contact Molly promptly with the petition, hearing date and correspondence so the available options can be assessed.
Talk to Molly about your HMRC arrears, your cash flow and the options available to your business.