Can I Put My Company into a CVL After Receiving a Winding-Up Petition?
A CVL may still be possible, but timing and court proceedings need careful coordination.
Read article →Close an insolvent company in a controlled, compliant way, with direct support from Licensed Insolvency Practitioner Molly Monks F.I.P.A.
Free initial advice · No obligation · Nationwide support
A Creditors’ Voluntary Liquidation is a formal insolvency procedure used when a company cannot pay its debts and its directors decide that it should stop trading and be wound up.
Unlike compulsory liquidation, which is usually started by a creditor through the courts, a CVL allows directors to take early action and begin an orderly closure. A licensed insolvency practitioner is appointed as liquidator to deal with company assets, creditors and the statutory process.
A CVL does not make personal guarantees disappear, and it is not suitable for every company. The first step is to understand the company’s full position and consider whether rescue, restructuring or closure offers the best outcome.
A CVL is often considered when the business is insolvent, recovery is no longer realistic and continuing to trade could worsen the position for creditors.
The company cannot pay wages, tax, rent or suppliers when payments fall due.
The value of the company’s liabilities is greater than the value of its assets.
Pressure has moved beyond reminders to statutory demands, court action or a winding-up petition.
Every situation is different. Our initial advice is free and confidential, so you can understand the options before making a decision.
Molly explains what directors can expect, how creditors are dealt with and what happens once a liquidator is appointed.
There is no pressure to proceed after an initial conversation. The aim is to give you a clear picture of the practical steps, likely costs and any issues requiring attention.
Download our free CVL guide →We manage the formal procedure and keep you informed throughout.
We review the company’s finances, pressures and objectives with you.
Molly considers whether rescue, restructuring or liquidation is most suitable.
If you proceed, we gather the information and prepare the required documents and notices.
Shareholders resolve to wind up the company and the creditor decision procedure is completed.
The liquidator takes control of company assets and communicates with creditors.
Assets are realised, claims are agreed and available funds are distributed in the statutory order.
Once the liquidation is complete, the company is dissolved and ceases to exist.
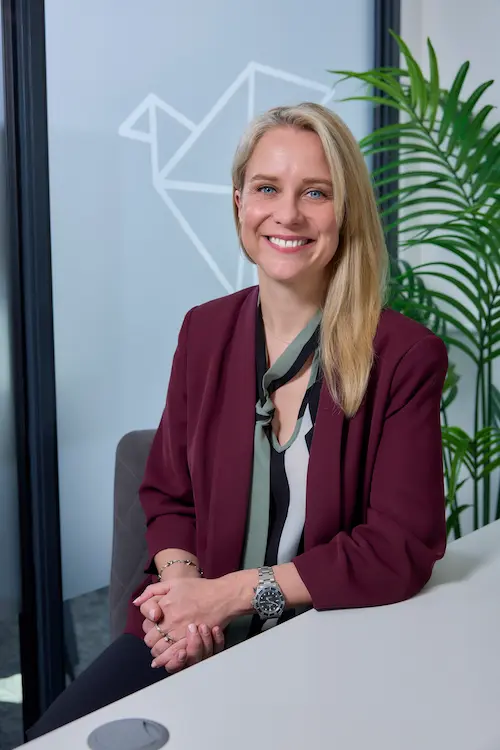
Molly is Parker Walsh’s founder and in-house Licensed Insolvency Practitioner. With more than 20 years’ experience, she gives directors practical, straightforward advice and remains closely involved throughout the process.
You will have direct access to specialist guidance, with a small and friendly team handling the detail around you.
Arrange a free, confidential chatAnswer a few questions about your company to receive an indicative quote. Molly will follow up personally if you would like to talk through it.
Complete the form below to get an instant indicative quote for your CVL.
Clear guidance on the questions directors most often ask before entering liquidation.
A CVL may still be possible, but timing and court proceedings need careful coordination.
Read article →Understand how an orderly closure can relieve pressure and clarify directors’ duties.
Read article →From consultation and notices to appointment, realisations and final closure.
Read article →Look at the warning signs, responsibilities and reasons early advice matters.
Read article →When company funds can usually be used and why proper authorisation matters.
Read article →If your question is not covered here, call us on 0161 546 8143. Initial advice is free and confidential.
The appointment process can often be arranged relatively quickly once the necessary information is available. The liquidation itself continues until assets, claims and statutory matters have been dealt with, so its overall duration varies.
Usually, yes. However, there are restrictions on reusing the same or a similar company name, and any director disqualification or personal circumstances must be considered.
Company debts are dealt with in the liquidation. Creditors receive any available distributions and, once the company is dissolved, it ceases to exist. Personal guarantees and personal liabilities are not automatically removed.
CVL costs are normally paid from company funds or asset realisations where these are available. We will explain the funding options and give you a clear quote before you decide to proceed.
HMRC can be included as a creditor in a CVL. The correct option still depends on the wider financial position, the viability of the business and whether an arrangement such as Time to Pay remains realistic.
Talk directly to Molly about your company’s position. There is no charge for an initial conversation and no obligation to proceed.